
9 Rental Property Tax Mistakes Investors Make in NZ
November 16, 2026 • Blog
Last Updated: November 15, 2026
Quick Summary
Rental property tax returns in New Zealand must declare all rental income, including late rent and advance payments, and claim only expenses the IRD allows. Common errors include omitting income, claiming capital improvements as repairs, and deducting private home loan costs.
- Declare the full year’s rent, including rent paid late and income received in advance.
- Claim loan interest, rates, insurance and management fees, but only for the rental portion.
- Capital improvements such as a new kitchen are generally not claimable in the year paid.
- Keep invoices, receipts and statements for the period Inland Revenue requires.
- Reconcile your rental account monthly to catch missing income and miscoded expenses early.
Table of Contents
- How Rental Income Is Taxed and What Your Return Needs
- Rental Property Expenses You Can and Cannot Claim
- Keeping Investment Property Tax Records That Hold Up
- Frequently Asked Questions
Rental property owners in New Zealand often assume their rental property tax return is a formality. It is not. The Inland Revenue Department (IRD) expects rental income to be declared in full, and expenses to be claimed only where the rules allow (Residential rental income and paying tax on it). Small errors, repeated across several years, can lead to amended assessments and penalties. This guide sets out the points where investors most often go wrong.
How Rental Income Is Taxed and What Your Return Needs
Rental income is taxable income. It is the gross rent you receive, plus any other payments tied to the property, such as bond amounts you keep or payments for letting fees you receive. Your rental income is added to your other income and taxed at your marginal rate.
Many investors make the mistake of declaring only the rent that landed in their bank account when filing rental property tax. Check the full year, including any rent paid late, and any income you received in advance for the next period.
Keep a schedule for each property. Record the rent received, the dates, and the address. This makes the rental section of your return straightforward to complete.
For a precise view of your obligations, Inland Revenue guidance on rental income sets out how rental income must be reported.
Rental Property Expenses You Can and Cannot Claim
Most investors can claim expenses that are necessary to earn rental income. Common examples include loan interest, rates, insurance, property management fees, and repairs that restore the property to its original condition. Because repairs are deductible only when they restore the property rather than improve it, investors should distinguish routine upkeep from capital work, including when considering King’s Choice Solutions.
Some items are often wrongly claimed. Improvements that add value or extend the property’s life are generally capital, not deductible repairs. Capital improvements such as a new kitchen are generally not claimable in the year they are paid.
A common mistake is claiming private costs, such as the portion of a home loan that relates to your own residence. Only the rental portion of costs can be claimed.
If you are unsure whether a cost is claimable, IRD guide to deductible rental expenses is a reliable starting point. A chartered accountant can confirm the treatment for your specific situation, and you can read more in our guide to hiring a chartered accountant for your tax return.
The article sets out which common costs are usually claimable and which are often claimed wrongly.
| Cost | Treatment | Note |
|---|---|---|
| Loan interest | Generally claimable | Rental portion only |
| Rates | Generally claimable | Necessary to earn rental income |
| Insurance | Generally claimable | Necessary to earn rental income |
| Property management fees | Generally claimable | Necessary to earn rental income |
| Repairs | Claimable if restoring original condition | Not improvements |
| New kitchen | Generally not claimable in year paid | Capital improvement |
| Home loan portion for own residence | Not claimable | Private cost |
Keeping Investment Property Tax Records That Hold Up
Good records make your return easier and protect you if the IRD asks questions. Keep invoices, receipts, bank statements, loan statements and property management reports for the period required by Inland Revenue.
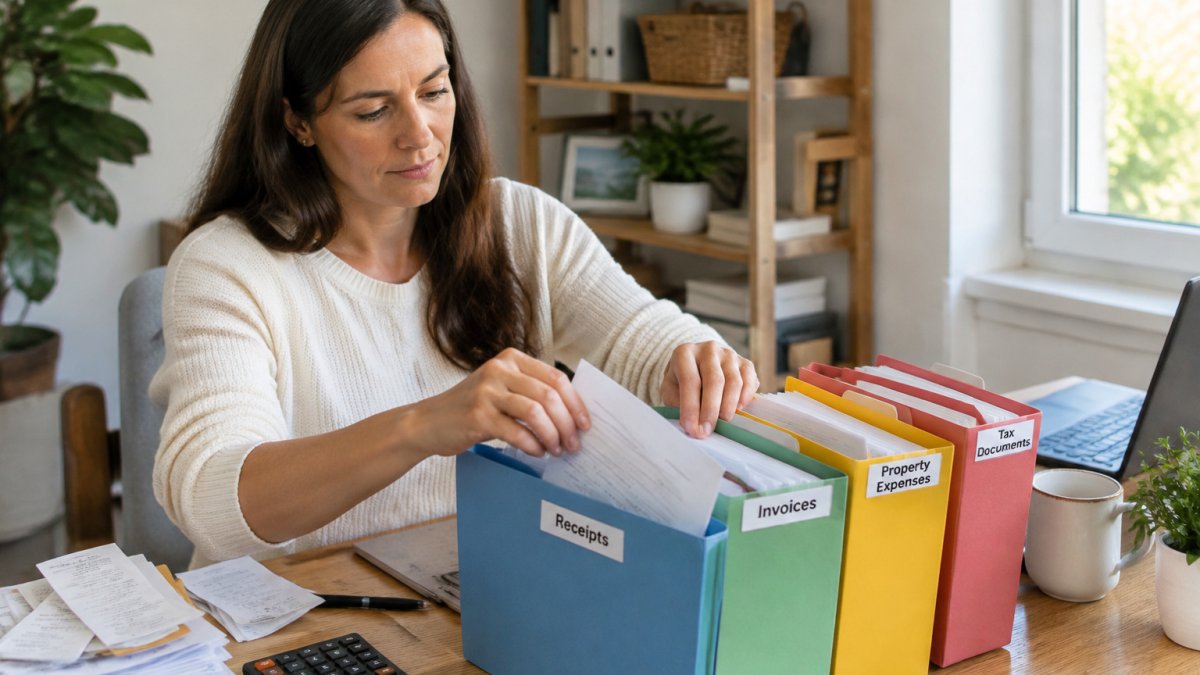
Store records in one labelled system. Separate folders for each property and each year work well. Photograph paper receipts on the day you receive them, so nothing is lost.
Reconcile your rental account monthly rather than once a year. This catches missing income and miscoded expenses early. If your records are becoming difficult to manage, our guide on choosing a business accountant explains what to look for, and our accounting services cover record keeping for property investors.
Frequently Asked Questions
What records do property investors need for a tax return?
Keep rent statements, loan statements showing interest paid, invoices for repairs and maintenance, rates and insurance notices, property management statements, and purchase and sale documents. Store them for as long as Inland Revenue requires. Digital copies are acceptable if they are clear and easy to retrieve. Organising records by property and by financial year makes preparing your return far quicker and reduces the risk of missed deductions.
What rental property expenses can I claim on my tax return?
Most costs incurred to earn rental income are deductible, including mortgage interest, rates, insurance, property management fees, advertising for tenants, body corporate levies, and repairs that restore the property to its original condition. Capital improvements, such as extensions or new kitchens, generally cannot be claimed in full in the year they are paid and are instead treated differently. Private costs and expenses for the period you did not rent the property are not deductible.
Do I need an accountant for my rental property tax return?
You are not legally required to use an accountant, but professional advice can help with the tax treatment of your rental properties. Professional advice is especially useful if you own properties in different structures or co-own with others. Macro Accounting, led by a Chartered Accountant, can review your position. For current fees, please visit our website or request a quote.
